If Someone Had to Step Into Your Shoes Tomorrow -


LifeSkills Academy Blog
Check back often to find interesting information and updates.
If Someone Had to Step Into Your Shoes Tomorrow -
Would They Know What to Do?
Imagine someone you treasure having to step into your shoes tomorrow. Not permanently. Not necessarily because the worst has happened. Perhaps an illness, accident, extended trip or unexpected circumstance simply means you can’t manage everything yourself for a while.
Would that person know where to begin? Could they find your important documents? Would they know whom to call? Which financial, insurance, legal or healthcare professionals are part of your support team? Would they know which information is current—and which folder hasn’t mattered since 2008?
Most of us have accumulated quite a lot while building a life. Some of it is treasure. Some of it is essential. Some of it is outdated. And somewhere in a drawer are charging cables belonging to devices no one has seen in twelve years.
The goal isn’t to perfectly organize an entire life.
The goal is to create a path someone else can follow.
Start With a Trusted Guide
Consider who could serve as your trusted guide—the person who knows where to begin if you’re unable to provide directions yourself. This doesn’t mean giving that person every password, account number, document or key. Nor does simply calling someone your trusted guide give them legal authority to act for you.
It means someone knows: There is a plan. Here is where it begins. Here are the people to contact.
That alone can remove an enormous amount of uncertainty. And before assigning someone this role, have the conversation:
“Would you be comfortable being the person who knows where my important information
is and whom to contact if I couldn’t handle things myself?”
It may feel awkward for a few minutes. But consider how much harder the conversation would be when circumstances have already taken the choice away.
Create a Map, Not a Mountain
This is where preparation can quickly become overwhelming.
Legal documents. Insurance. Bank and investment accounts. Medical information. Property records. Passwords. Household obligations. Digital accounts.
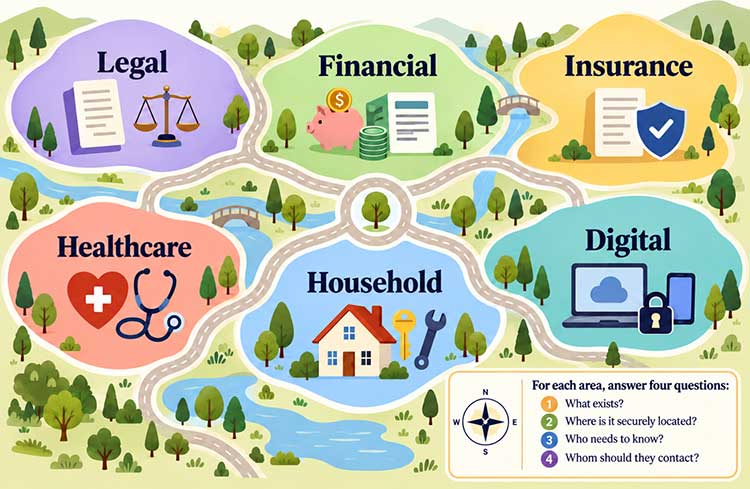
Instead of beginning by gathering everything, begin by mapping what exists.
Your map might contain six broad areas:
Legal. Financial. Insurance. Healthcare. Household. Digital.
For each one, answer four questions:
- What exists?
- Where is it securely located?
- Who needs to know?
- Whom should they contact?
The map itself doesn’t need to contain every sensitive detail. In many cases, it may simply tell the appropriate person where information can be securely found. Think of it as the index to your life—not the entire encyclopedia.
Give the Right People the Right Authority
Knowing where something is and having legal authority to act are two very different things.
That’s where professional legal guidance may belong on your financial support team. Depending upon your circumstances and the laws where you live, an attorney can help you understand documents such as a will, financial power of attorney, healthcare power of attorney or healthcare directive—and how beneficiary designations and other arrangements interact with your plans.
The important questions underneath the terminology are much simpler:
- Who can act for me financially if I cannot?
- Who can make healthcare decisions if I cannot speak for myself?
- Have I documented my wishes?
- Who will handle my affairs after my death?
- Do my documents still reflect the life I’m living today?
The precise documents and requirements vary by jurisdiction, which is one reason this is an area where qualified legal guidance matters. For example, Washington State’s court system distinguishes formal guardianship and conservatorship proceedings and advises people who need legal advice to consult a lawyer or legal-services program.
We don’t need to become legal experts. We need to recognize the questions that deserve expert answers.
Make Sure Everyone Knows They’re in Your Script
A beautifully prepared document isn’t much help if nobody knows it exists.
Talk with the people you’ve named. Make sure they’re willing to serve. Tell your trusted guide where appropriate documents are kept and which professionals should be contacted.
This is also a good time to determine whether something significant has changed. Marriage or divorce? Children or grandchildren? A move? Retirement? A new home? A business? The death of someone named in a document? A changed relationship?
A document created years ago may still be appropriate. The question is simply worth asking.
Keep the Trail Clear
Here’s where legal preparedness unexpectedly meets another LifeSkill: personal organization.
Professional organizer Elisa Hawkinson shared with LifeSkills Academy the story of a couple overwhelmed by decades of accumulated belongings as they prepared to move. Her recommendation was refreshingly manageable: regularly “edit” the contents of the home rather than waiting until circumstances force everything to be handled at once.
Our important information deserves similar attention. Once or twice a year—or at whatever rhythm works for you—ask:
What’s changed? What’s outdated? What’s accumulated? What would confuse someone else?
Clear obsolete paperwork. Update contacts. Review your information map. Dispose of sensitive documents appropriately. Revisit possessions that no longer serve you but could serve someone else. Keep the treasures.
One of the kindest things we can give the person who may someday step into our shoes is a trail that doesn’t require detective work.
This Is a Love Gift
There is something deeply considerate about preparing another person to carry responsibility on our behalf. We’re saying: “I know this may someday be difficult. I care about you enough to make the path a little easier.”
That changes this from a gloomy legal chore into an act of stewardship.
You don’t need to complete everything this weekend. You don’t need matching binders, a color-coded filing system or an afternoon appointment with those mysterious charging cables.
Just begin.
A Gentle Practice
Imagine that tomorrow someone you trust needs to step into your shoes. Where would they begin? If you already have an answer, make sure your trusted guide knows it. If you don’t, choose one safe starting place.
Write down what that person would need to know first. Then build outward—one category, one conversation and one decision at a time.
You aren’t organizing your entire life today. You’re simply making the next step findable.
“Where there is no [wise, intelligent] guidance, the people fall [and go off course like a ship without a helm],
But in the abundance of [wise and godly] counselors there is victory.”
Proverbs 11:14, Amplified Bible
If you're interested in LifeSkills Academy’s classes, valuable life skills content, and updates, we encourage you to sign up for our newsletters and class notices. Join us on the journey of continuous learning and personal growth. Together, let's build a foundation for success in life and our world.
Are You Covered for the Life You`re Actually Living?
You may have homeowners or renters’ insurance. Auto insurance. Health insurance. Perhaps life or disability coverage too. So, yes—you are insured.
But here’s a different question: Are you covered for the life you’re actually living? Because the life you insured several years ago may not be the life you’re living today.
You may have changed jobs, renovated your home, started working remotely, bought expensive equipment, welcomed children, added a teenage driver, started a business, accumulated assets or moved toward retirement. Meanwhile, the policies may have quietly renewed year after year.
Having insurance in place is important. Understanding whether that insurance still fits what you’re protecting is another matter. And that is a LifeSkill.
Start With Your Life, Not the Policy
Insurance paperwork can make us feel as though we should begin by deciphering deductibles, limits, endorsements and exclusions.
Try beginning with something you already understand: Your life.
Ask: What am I protecting? Your home? Vehicle? Income? Belongings? Business? Savings? The financial well-being of people who depend on you?
Then ask the question that may uncover the bigger issue: What has changed since I chose this coverage? You’re not trying to determine whether you have the “right” insurance by yourself.
You’re preparing to have a better conversation
with someone qualified to help you evaluate it.
Your Insurance Stability Check
Before contacting your insurance professional, gather your current policies and make a few notes. You don’t need an elaborate spreadsheet or a weekend retreat with your filing cabinet.
For each policy, consider four things:
- What am I protecting? Identify the purpose of the policy. What financial disruption is it intended to help you manage
- What has changed? Look at your life since the coverage was established or last carefully reviewed. New people, property, responsibilities, income, assets, work arrangements or major purchases may deserve discussion.
- What don’t I understand? Circle unfamiliar terms. Note deductibles, limits or provisions you’re unsure about. Write down assumptions you’ve been making.
- Who can help me answer it? That may be your insurance agent or broker. More complex financial, business or estate circumstances may also involve other qualified professionals.
Now you’re ready for a different kind of insurance conversation.
Bring Your Side of the Equation
Imagine walking into a meeting and simply asking: “Do I have enough insurance?” That places almost the entire conversation in someone else’s hands.
Instead, you can arrive saying: “Here’s what I currently have. Here are the changes since we established this coverage. Would you help me understand whether my policies still match the risks I’m trying to protect?”
Now there are two kinds of expertise at the table. The professional understands insurance. You understand your life. Together, you have a much better starting point.
Don’t Stop at the Definition
Insurance has its own vocabulary. Deductible. Liability. Exclusion. Replacement cost. Actual cash value. Coverage limit. Endorsement. A professional may explain those terms accurately—and you may still leave wondering what they mean when something actually happens.
That’s when another LifeSkill becomes useful:
Try: “Would you give me an example of when that would apply?” Or: “If that happened to me, would you walk me through what I would be responsible for, what the policy might pay and where the coverage would stop?”
- Suppose your policy has a deductible. Instead of merely learning its definition, ask your professional to walk you through how that deductible could work in a covered claim.
- If replacement cost and actual cash value come up, ask for an example showing how the two could produce different results.
- If you’re discussing liability protection, ask for examples of situations where the coverage might respond—and where it might not.
You’re not asking for an insurance lecture. You’re asking someone to translate policy language into a situation you can understand.
Ask About the Assumptions
Here may be one of the most valuable questions in the entire conversation: “What do clients commonly think this covers that it actually doesn’t?”
Insurance misunderstandings can hide inside assumptions:
- Maybe you believe a particular kind of property is fully protected.
- Perhaps you assume an event is covered because something similar would be.
- Maybe you’ve never considered where a coverage limit ends or when an exclusion applies.
Finding that out during a calm review is considerably better than discovering it after a loss.
Another useful question is:
“What circumstances should cause me to review this policy again?” Now you’re not just reviewing today's coverage. You’re learning when to revisit it.
Understanding Is Part of the Job
There’s no prize for nodding knowingly through a conversation you don’t understand.
If the terminology starts outrunning you, stop. Say: “I’m not sure I understand that yet. Would you put it into a real-life situation for me?”
That isn’t challenging the professional’s expertise. It’s participating responsibly in a decision that affects your financial stability. Your insurance professional can explain available coverage, provisions and options. Your responsibility is to keep asking until you understand enough to make an informed decision about your own circumstances.
“A wise man will hear and increase learning, And a man of understanding will attain wise counsel…”
- Proverbs 1:5
The goal isn’t more insurance.
The goal is appropriate protection you understand.
From Filing Cabinet to Stability Plan
Insurance may never become your favorite Saturday afternoon reading. That’s okay. You don’t need to memorize your policies or become fluent in insurance terminology.
You need to know what you’re protecting, recognize when your life has changed, identify what you don’t understand and bring good questions to people who can help.
That moves insurance from something sitting quietly in a filing cabinet to something more useful: part of your Stability Plan.
Gentle Practice: Your Four Moves
Choose one policy this week. Then answer:
- What am I protecting?
- What has changed since this coverage was established or last reviewed?
- What don’t I understand?
- Who can help me answer it?
If a conversation follows, take one additional question with you:
5. “Would you show me what this means in a real-life situation?”
You don’t need to know everything about insurance.
But you do need to understand enough about your own coverage to know what you’re counting on.
If you're interested in LifeSkills Academy’s classes, valuable life skills content, and updates, we encourage you to sign up for our newsletters and class notices. Join us on the journey of continuous learning and personal growth. Together, let's build a foundation for success in life and our world.
What Financial Advisors Actually Do
(& When You Need One)
For some people, following the stock market is fascinating. For others, it ranks somewhere between reorganizing the garage and reading the fine print on an insurance policy.
Fortunately, responsible financial management doesn’t require making money your hobby. It does require knowing enough to make sound decisions, recognize when you need expertise, and choose trustworthy people to help you.
Perhaps that’s the most useful way to think about financial advice:
You don’t have to become the financial expert on your team.
You do need to remain the leader of the team.
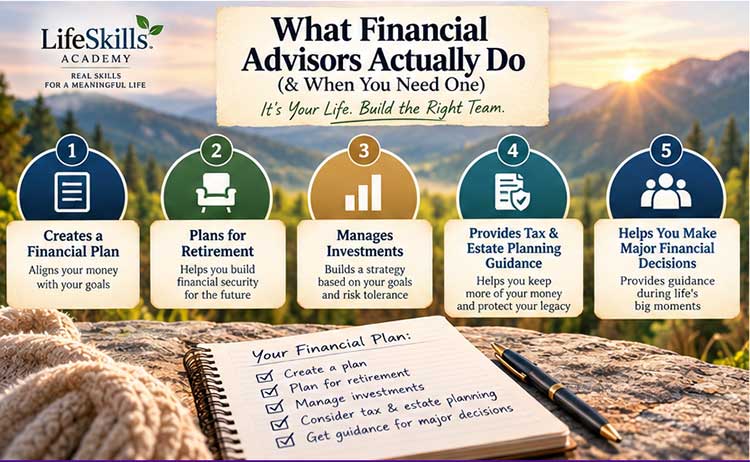
What Does a Financial Advisor Actually Do?
“Financial advisor” sounds like one clearly defined profession. In reality, people using financial-advice titles may provide very different services. Some focus primarily on investments; others provide broader planning across retirement, taxes, insurance, estate considerations and long-term goals.
So before searching for an advisor, start somewhere else: What do I actually need help with?
Someone approaching retirement may need different expertise from a young family balancing debt, savings and insurance. A business owner may need another combination entirely.
Start with the need. Then look for the expertise.
Delegating Isn’t Abdicating
Here’s good news for those who don’t particularly enjoy studying investments: You don’t need to know everything your financial professionals know. That’s why expertise exists.
Think about leadership in any other setting. A good leader doesn’t need to perform every specialized job. The leader needs to understand the objective, choose capable talent, communicate priorities, ask good questions and recognize when different areas of expertise need to work together.
Your financial life isn’t much different.
An advisor may understand investments better than you do. Your CPA understands taxes. An insurance professional understands risk and coverage. An attorney may understand estate-planning structures.
But you know the life all of that expertise is supposed to serve.
That keeps you in the leadership seat.
A healthy relationship should allow you to say: “I don’t need to know everything you know. I do need to understand why and what you’re recommending.” Why this investment? This amount of risk? This insurance coverage? This strategy now?
Good delegation doesn’t mean handing over responsibility. It means putting expertise to work while remaining sufficiently informed to make the ultimate decisions.
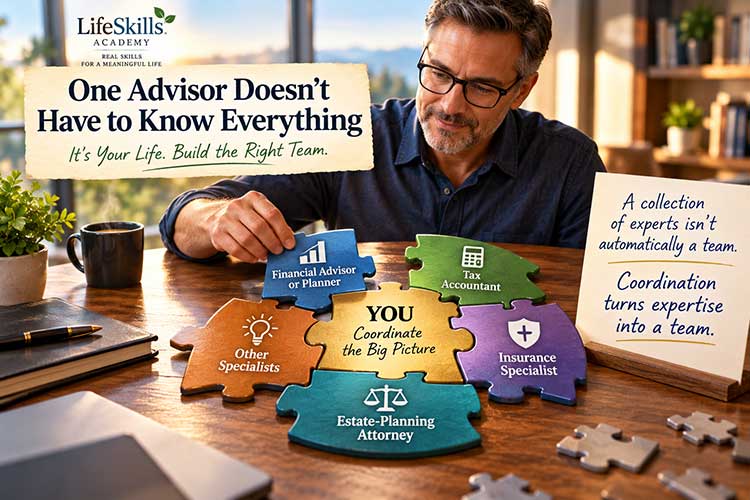
One Advisor Doesn’t Have to Know Everything
Your financial needs may eventually involve several kinds of expertise. Your financial “bench” might include a financial advisor or planner, CFP® or an investment professional, tax accountant, insurance specialist or estate-planning attorney. And financial services continue to evolve. Emerging areas may sometimes require specialized knowledge beyond someone’s traditional training.
That doesn’t mean everyone needs a financial team worthy of their own conference room.
The goal isn’t to collect experts.
It’s to have the right expertise available for the
decisions you’re actually making.
Those professionals may work in different offices—or different parts of the country—and may not automatically know what the others are doing. Someone needs to recognize when their areas intersect. That someone begins with you.
A collection of experts isn’t automatically a team. Coordination turns expertise into a team.
Choosing Someone for Your Team
Credentials matter. So do philosophy, communication and trust. Before choosing someone, consider asking:
- What services will you actually provide?
- What experience do you have with people in circumstances like mine?
- How are you compensated, and what will I pay?
- When advising me, are you acting as a fiduciary?
- How will you explain recommendations and potential downsides?
- What happens when I need expertise outside your specialty?
Then notice more than the answers.
Does the person ask what matters to you before recommending strategies or products? Can they explain why? Will they tell you when something falls outside their expertise?
Trust grows when competence, transparency and
communication repeatedly give you good reason for it.
Money Is the Servant, Not the Master
This may be the most important perspective of all. The purpose of financial management isn’t necessarily to accumulate the largest possible number.
Money can provide security, prepare us for retirement, educate children, care for family, support causes we value, weather emergencies, create opportunities and build a legacy.
Those purposes affect what financial success looks like.
A good financial professional needs to understand what you want your money to accomplish in your life, not simply how much more of it might be accumulated.
Your values establish the destination.
Financial expertise helps you navigate toward it.
Put Your Financial Team on Paper
Here’s this week’s Gentle Practice. Take five minutes and sketch your current financial bench:
YOU — Team Leader: ____________
o Financial planning → __________
o Investments → __________
o Taxes → __________
o Insurance → __________
o Estate/legal → __________
o Other specialized expertise → __________
Empty spaces aren’t automatically problems. You may not need every kind of professional. Instead, look at the whole picture and ask:
✓ Do I know who handles what?
✓ Do the people advising me understand what matters to me?
✓ Do I understand why I’m following their recommendations?
✓ Would I know whom to call if an important financial question arose tomorrow?
✓ Do I recognize where the responsibilities of two team members might intersect?
You don’t have to become fascinated with finance to steward your resources well.
Know the life you’re building.
Choose expertise carefully.
Coordinate it when necessary.
Stay engaged in important decisions.
And remain the leader of the team.
Next Up: One Seat Worth Examining
There’s one line on that financial bench many of us can fill in—but may not be able to explain very well: Insurance.
We buy it hoping we won’t need it, sometimes carrying policies for years without revisiting them.
Next week, we’ll look at what kinds of insurance belong in a sound financial life, how much may be enough, and what questions we should be asking.
For now, there’s no need to master every financial specialty.
Know the life you’re building. Know who’s helping you build it.
And keep money in its proper place—serving the mission, never becoming the master.
“Let the wise listen and add to their learning and let the discerning get guidance.” — Proverbs 1:5
If you're interested in LifeSkills Academy’s classes, valuable life skills content, and updates, we encourage you to sign up for our newsletters and class notices. Join us on the journey of continuous learning and personal growth. Together, let's build a foundation for success in life and our world.
Most Recent Posts ...
Posted on: 10/26/2026
Posted on: 10/19/2026
Posted on: 10/12/2026
Posted on: 10/5/2026
Search All Blog Posts
Blog Post Archive Categories
- You're Not Where You Were in January
- Teaching Financial Awareness to Children & Young Adults
- Transparency, Trust & Shared Responsibility
- If Someone Had to Step Into Your Shoes Tomorrow -
- Are You Covered for the Life You`re Actually Living?
- What Financial Advisors Actually Do
- Halloween Etiquette: Teaching Respect and Community Spirit
- Words of Wisdom: Traveling 2024
- Thankful Thursdays
- My interview with Dennis Pearce